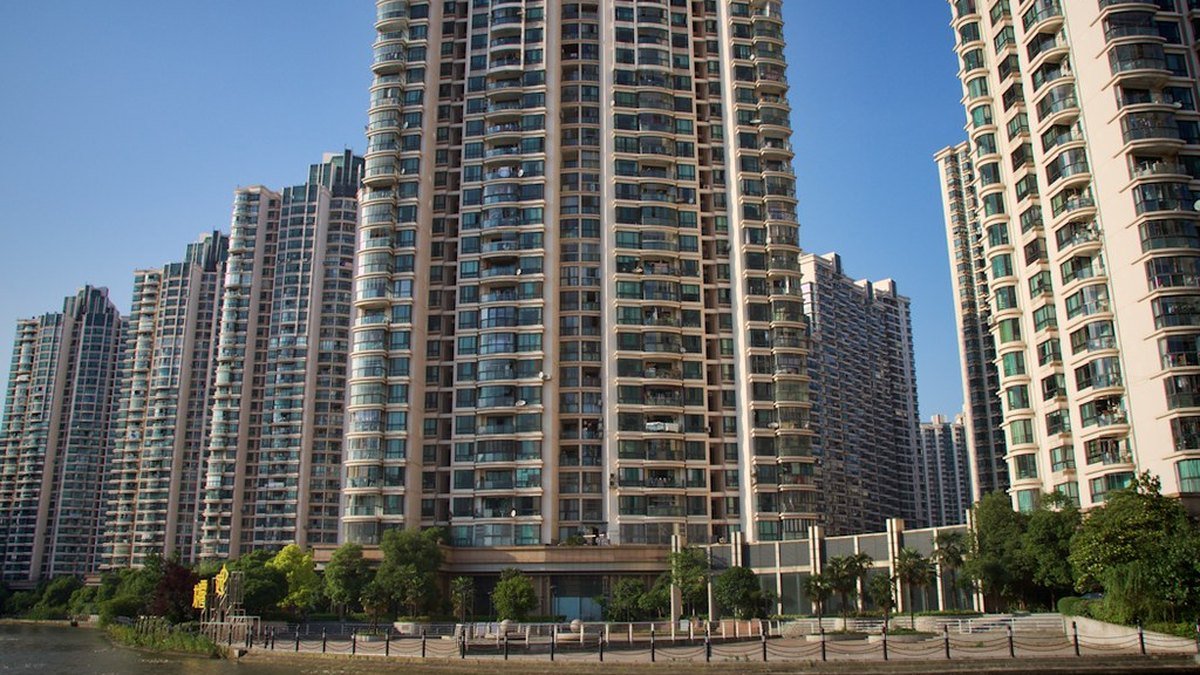
Few subjects in the global economy attract as much attention as China’s property sector. For years it was a powerful engine of growth; more recently it has been a source of strain and uncertainty. Because China is the world’s second-largest economy and a huge consumer of raw materials, what happens to its housing market ripples far beyond its borders. This guide explains, in plain terms, how the sector grew so large, why it ran into trouble, and why investors everywhere keep a close eye on it.
Key takeaways
- Property grew into one of the largest components of China’s economy.
- Many developers relied on pre-selling homes and borrowing heavily to fund growth.
- Housing became the main store of wealth for Chinese households.
- Local governments leaned on land sales for a big share of their revenue.
- China’s property cycle affects global commodity demand and exporters across Asia.
How property became so central
Over several decades of rapid urbanisation, hundreds of millions of people moved from the countryside to China’s cities, creating enormous demand for housing. Construction boomed, and property swelled into one of the biggest parts of the economy once you count everything connected to it: building work, cement and steel, appliances and furnishings, and the land sales that funded local governments.
Just as important, homes became the primary way Chinese families stored their savings. With limited alternative investment options, households poured wealth into apartments, which tied family finances tightly to property prices. That dynamic made rising home values feel like a one-way bet — and made any slowdown far more consequential for ordinary people.
The business model — and where it strained
Pre-sales and leverage
Many developers grew using a model built on pre-sales and debt. They would sell apartments before they were finished, collecting cash from buyers up front, and borrow heavily on top of that. The incoming money funded land purchases and new projects, which generated more pre-sales — a fast-spinning cycle that worked beautifully as long as prices rose and credit flowed freely.
When the cycle slowed
The model’s weakness is that it depends on continuous momentum. When borrowing limits were tightened to curb excessive risk, and when sales cooled, some heavily indebted developers found themselves short of cash. A few struggled to complete apartments that buyers had already paid for, which dented public confidence. Falling confidence led to weaker sales, which put further pressure on developers — the cycle running in reverse.
- Developers relied on pre-sales and large amounts of borrowing.
- Local governments depended on land-sale revenue to fund services.
- Household wealth is unusually concentrated in housing.
- Confidence is self-reinforcing — in both directions.
Why the rest of the world watches
China’s construction boom made it the world’s dominant buyer of commodities such as iron ore and copper. When Chinese building activity rises or falls, it moves global prices for those materials — which is one reason Australia’s resource-heavy market is so sensitive to Chinese demand (see our explainer on Australia’s critical minerals). Multinational companies that sell into China, and exporters across the Asia-Pacific, also feel the effects through their sales and earnings, which can show up in benchmarks covered in our guide to Asia’s stock indices.
Beijing’s balancing act
The central challenge for policymakers is to stabilise the sector without reinflating the old risks. Support the market too aggressively and the debt-fuelled excesses could return; withdraw support too sharply and the slowdown could deepen and spread to the wider economy. Managing that trade-off — while gradually steering households and local governments toward less property-dependent sources of wealth and revenue — is one of the defining economic tasks facing China.
How the slowdown affects ordinary households
Because so much Chinese family wealth is tied up in property, a cooling market is felt directly in household finances. When home values stop rising, people can feel less wealthy and become more cautious about spending — an effect economists call the ‘wealth effect’ working in reverse. Buyers who paid in advance for apartments that were delayed experienced the strain most acutely, and uncertainty of that kind can make families save rather than spend, which in turn weighs on the broader economy.
This connects housing to consumer demand across the economy, from cars and appliances to travel — the very demand that makes China so important to exporters around the Asia-Pacific.
What a healthier model could look like
Economists broadly agree that a more sustainable path involves less reliance on property as both a growth engine and a store of household wealth. That could mean a larger role for other forms of saving and investment, more stable and transparent developer financing, and local-government revenue that depends less on land sales. The transition is difficult precisely because property became so central, but steering gradually toward a more balanced model is widely seen as the key long-term task.
- Reduce the economy’s dependence on construction and land sales.
- Give households more ways to save beyond housing.
- Put developer financing on a steadier, more transparent footing.
Frequently asked questions
Why is China’s property sector so important to its economy?
Property and its related industries — construction, materials, appliances and local-government land sales — grew into one of the largest parts of China’s economy, and housing became the main store of household wealth.
What is the pre-sale model?
Under the pre-sale model, developers sell apartments before they are built and use the upfront cash to fund more projects. It supports rapid growth when demand is strong but creates risk if sales slow before homes are completed.
How does China’s property market affect other countries?
China is the world’s largest consumer of commodities such as iron ore and copper, so its construction cycle influences global prices and the earnings of exporters and multinationals, particularly across the Asia-Pacific.
Why do local governments in China care about property?
Local governments have relied on revenue from selling land to developers to help fund public services, so a slowdown in property affects their finances too.
The bottom line
China’s property sector is a story of a growth engine that became so large, and so interwoven with household wealth and local finances, that managing its ups and downs is now central to the whole economy. For the rest of the world, it remains one of the most important variables to watch in the Asia-Pacific.
1 thought on “Understanding China’s property sector and why it matters”