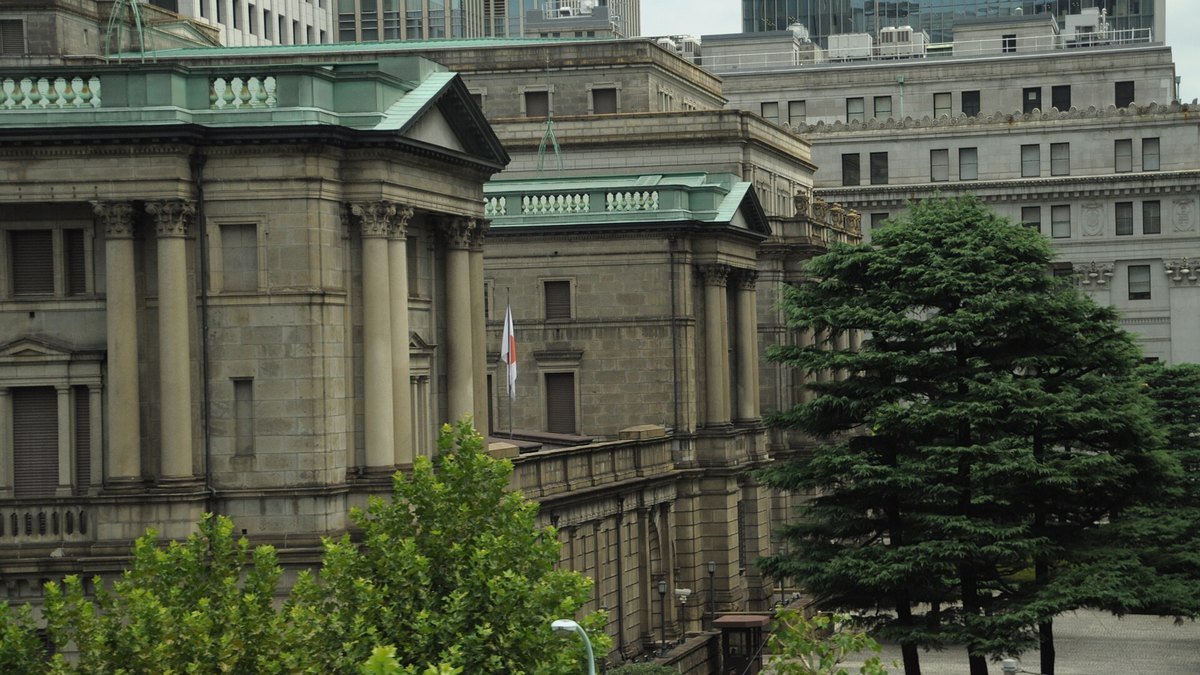
For much of the past generation, Japan stood apart from every other major economy by keeping interest rates extraordinarily low — at times even below zero. Understanding why the Bank of Japan pursued that policy, and why moving away from it is such a delicate task, helps explain moves not just in Tokyo but in currency and bond markets around the world. This explainer covers the history, the mechanics and the global stakes in plain language.
Key takeaways
- Japan battled years of falling or flat prices after its 1990s asset bubble burst.
- Ultra-low rates and large-scale bond buying were meant to revive spending and inflation.
- The gap between Japanese and foreign interest rates heavily influences the yen.
- A weaker yen helps exporters and tourism but raises import costs.
- Markets watch every signal from the Bank of Japan for global ripple effects.
Why Japanese rates stayed so low for so long
The story begins with the bursting of a massive asset bubble in the early 1990s. In the aftermath, Japan experienced long stretches of deflation — falling or stagnant prices — which is far more damaging than it sounds. When people expect prices to fall, they delay spending, companies hold back on investment, and the economy can get stuck in a low-growth rut.
To fight that, the Bank of Japan pushed interest rates down to rock-bottom levels and, when that was not enough, bought enormous quantities of government bonds and other assets to hold down longer-term borrowing costs. The goal was to encourage borrowing and spending and to nudge inflation up toward a stable, modest target — the opposite of the deflationary mindset the country was trying to escape.
What changes as policy normalises
As the central bank edges away from ultra-loose settings, the effects reach well beyond Japan. The single most important channel is the interest-rate gap between Japan and other major economies.
The yen and the carry trade
When Japanese rates are far below those abroad, investors can borrow cheaply in yen and move the money into higher-yielding assets elsewhere — a strategy often called the carry trade. That tends to push the yen weaker. As the gap narrows, those flows can reverse, strengthening the yen, sometimes sharply. Because these positions are large, shifts in expectations about Japanese policy can move global markets quickly.
Winners and losers from a weak yen
A weaker yen is not simply good or bad — it redistributes:
- Exporters benefit, because their goods become cheaper abroad and foreign earnings translate into more yen.
- Tourism gets a boost, as Japan becomes cheaper for overseas visitors.
- Importers and households feel the squeeze, because imported energy, food and raw materials cost more.
Those export-heavy fortunes also feed into Japanese equities — see how benchmarks such as the Nikkei 225 are built in our guide to Asia’s major stock indices.
The global ripple effects
Japan is one of the world’s largest holders of overseas assets, so decisions in Tokyo influence global bond markets. If Japanese government bond yields rise, some domestic investors may bring money home rather than hold foreign bonds, which can nudge borrowing costs elsewhere. This is why traders across the Asia-Pacific — and well beyond — parse every statement from the Bank of Japan so closely.
The balancing act
Normalising policy after decades of extreme stimulus is genuinely difficult. Move too quickly, and a fragile recovery could stall and deflationary habits could return. Move too slowly, and the currency and prices can swing uncomfortably. The central bank has to weigh domestic wages and prices against currency stability and global conditions — all while markets hang on its every word. That careful, gradual approach is precisely why Japan’s monetary policy remains one of the most watched stories in global finance.
What it means for households and businesses in Japan
Monetary policy is not an abstraction for people living in Japan. Ultra-low rates kept borrowing cheap for a long time, benefiting companies and home-buyers but offering savers very little return. As policy normalises, borrowing costs can edge up, savers may finally earn more on deposits, and businesses have to adjust their plans accordingly. A weaker yen, meanwhile, raises the cost of imported energy and food, which households feel directly in their bills.
Because these effects pull in different directions — helping some groups while squeezing others — the central bank has to move carefully to avoid destabilising either the economy or prices.
What global investors watch for
Investors around the world monitor Japan for signals about the direction of its interest rates and bond yields, and about the yen. Shifts in those variables can ripple into global markets, because strategies that borrow cheaply in yen are widespread and Japan is a very large holder of overseas assets. The key things market-watchers track include:
- The gap between Japanese and foreign interest rates, which drives the yen.
- Movements in Japanese government bond yields.
- Signals about the pace of any policy normalisation.
For how currency moves feed into equity markets, see our guide to Asia’s major stock indices.
Frequently asked questions
Why did the Bank of Japan keep interest rates so low?
After its asset bubble burst in the early 1990s, Japan faced long periods of deflation. Ultra-low rates and large-scale bond buying were intended to encourage spending and investment and to lift inflation toward a stable target.
How do Japanese interest rates affect the yen?
The gap between Japanese rates and rates abroad is a major driver of the yen. A wide gap tends to weaken the yen as investors seek higher yields elsewhere, while a narrowing gap can strengthen it.
Is a weak yen good or bad for Japan?
It depends who you are. A weak yen helps exporters and tourism but raises the cost of imported energy, food and materials, which squeezes households and import-dependent businesses.
Why do global markets care about the Bank of Japan?
Japan is a very large holder of overseas assets, and strategies that borrow cheaply in yen are widespread. Shifts in Japanese policy can therefore move currencies and bond markets around the world.
The bottom line
The Bank of Japan’s long experiment with ultra-low rates was a response to decades of deflation, and unwinding it is a careful balancing act with global consequences. Because Japan’s policy moves ripple through the yen and world bond markets, the slow road back to normal remains essential watching for anyone following the Asia-Pacific economy.
2 thoughts on “The Bank of Japan’s long road away from ultra-low rates”